The recent avalanche of investment into global sports assets from private capital and private wealth is well publicised. Investors continue to value sport’s defensive qualities, as the unscripted, human drama of a live contest offers a counterweight to AI’s growing disruption of traditional businesses.
That confidence has translated to a run of large deals. Over the summer, Clearlake Capital agreed to buy out Todd Boehly and Mark Walter’s combined 25% stake in Chelsea FC at a c. £5bn valuation, Arctos agreed its fourth NFL stake with the Atlanta Falcons, Apollo proposed putting €1bn into the Bundesliga, and a consortium led by the Mittal family and Adar Poonawalla agreed to buy the Rajasthan Royals and its sister franchises for $1.65bn, while FIFA proposed (and later dropped) selling interests in its commercial and event operations (including FIFA World Cup), pooled into an investment vehicle valued at c. $20bn.1
These headline deals reflect a wider pattern in the market, with deal volumes falling as deal sizes rise. What is driving this trend?
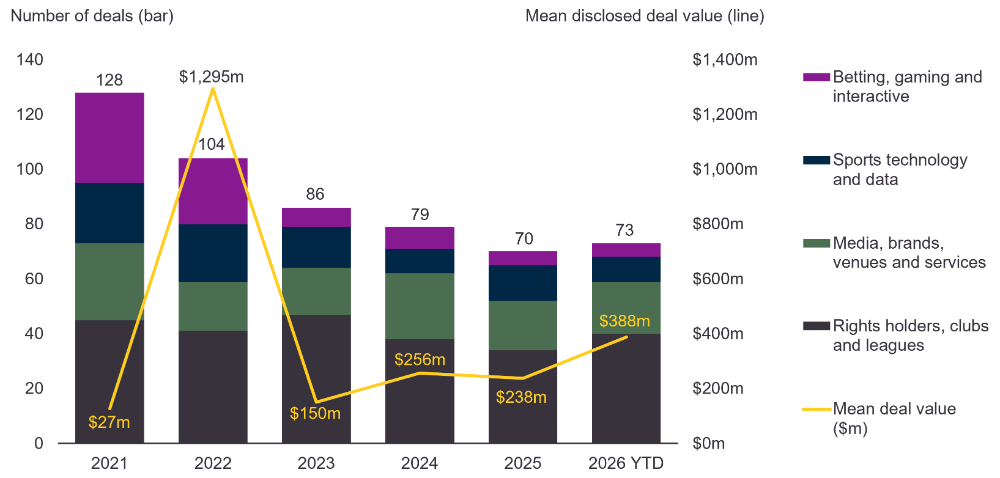
Source: Macfarlanes analysis of Preqin private equity deals exports, including: 540 sports transactions, from 1 January 2021 to 12 October 2026. Captures deal volume by segment against mean disclosed deal value, with 2026 YTD at October 12, 2026. The median was $10.4m–$28.3m in each year. Note: the 2022 figure is an outlier due to Microsoft’s $68.7bn Activision Blizzard deal.
- Valuations have outrun the buyer pool. Franchise values have compounded at roughly 13% per year over six decades, outpacing the capacity of individual owners. As entry prices rise, fewer parties can write those cheques. Those that can are concentrating larger sums in premium assets with contracted league-level cash flows, where monetisation is more proven than in emerging leagues or lower tiers.2
- League rules keep the buyer pool small. North American leagues admit institutional capital mainly through capped, passive minority stakes (15% per fund in MLB, 10% in the NFL), so a small group of approved large-cap specialists, led by Arctos, Ares and Sixth Street, continues to execute a concentrated stream of large deals.3
- Owners are equity-rich but illiquid. Teams are financed at around 10% loan-to-value, against 40–70% in other asset-intensive sectors, as league debt limits and a tradition of equity funding have left value locked in franchise balance sheets. Owners seeking liquidity have mainly, therefore, turned to minority stake sales, while borrowing remains a little-used alternative, with only 27 private debt financings in sport recorded between 2021 to 2026 YTD.4
Looking ahead
These dynamics create opportunities across the market, from minority stakes in premium franchises to structured equity, preferred equity and private credit for equity-rich owners who need liquidity without selling control.
Consortia and co-investment pooling vehicles (often with athlete participation) become increasingly prevalent, as even large-cap sponsors and UHNW seek to spread equity risk a little – but without losing control.
Experienced advisers can help investors and owners capture these opportunities by negotiating minority protections and exit routes that work within league rules, structuring financing that fits league debt limits, and testing how durable an asset’s revenue really is, whether that rests on long-term media deals or on newer, less proven income streams.
Footnotes
1 Chelsea FC, Chelsea announces ownership transition, 16 September 2026; Non-Billable, ‘Sidley, Latham, Macfarlanes score roles on £950m Chelsea deal’, 17 September 2026 (Macfarlanes advised Hansjörg Wyss, who retains his stake); CNBC, ‘Arctos agrees to buy 10% of Atlanta Falcons at $10.6 billion valuation, sources say’, 20 August 2026; Private Equity Wire, ‘Bundesliga explores EUR 1bn financing proposal from Apollo Sports Capital’, 28 July 2026; Macfarlanes, ‘Macfarlanes advises Rajasthan Royals on $1.65bn sale’, 5 May 2026; CNN, ‘FIFA scraps controversial $20 billion World Cup investment plan’, 31 July 2026; Al Jazeera, ‘FIFA forced to scrap World Cup private investment plan after backlash’, 31 July 2026.
2 Apollo, ‘The Financing Gap in Sports’, 2025. p. 10-11; Macfarlanes analysis of Preqin data (Arctos 19, Ares 16 and Sixth Street 8 deals).
3 Ibid.
4 Apollo, ‘The Financing Gap in Sports’, 2025 p. 16; Financial Times, ‘Fans, franchises and the big four’, 10 September 2026 (Arctos Partners); Macfarlanes analysis of Preqin private debt data, January 1, 2021, to October 12, 2026
Macfarlanes is a pre-eminent law firm advising a global client base across Private Capital, Private Wealth, M&A and Disputes.
Visit our website to learn more about our services and how we can assist.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]