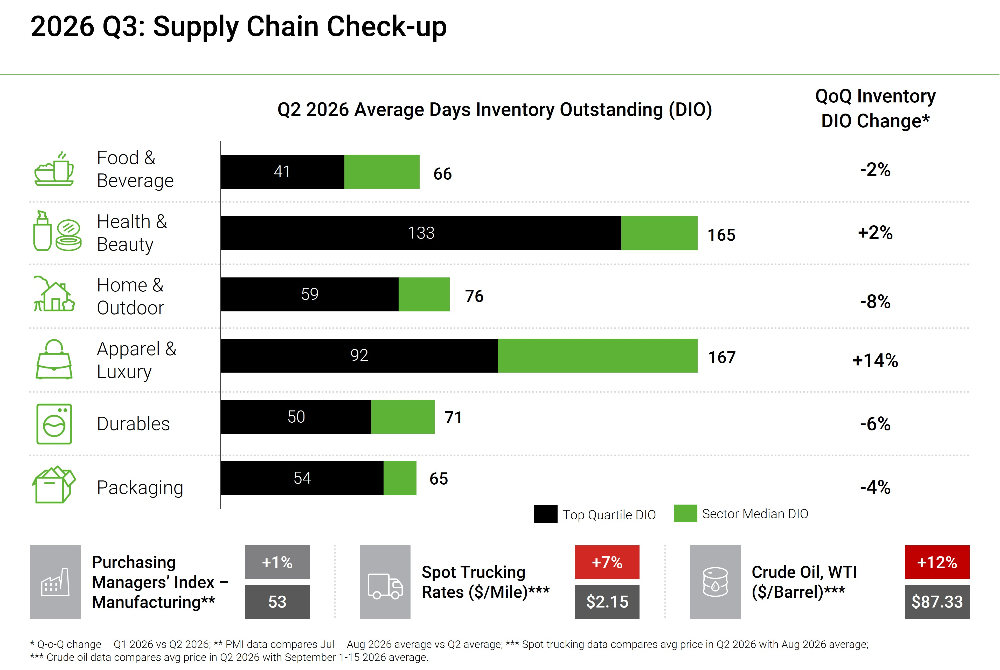
Discretionary categories drove a divergence in inventory positions in Q2, with Apparel & Luxury sector median DIO expanding 14% to 167 days and Health & Beauty edging up 2% to 165 days, as brands pulled imports forward ahead of tariff deadlines and softer end-demand slowed sell-through. Big-ticket sectors moved the other way: Home & Outdoor drew down 8%, Durables 6%, and Food & Beverage 2%, reflecting weaker housing turnover, cautious replenishment, and continued working-capital discipline. Top-quartile operators held their edge, with Food & Beverage at 41 days (38% below the sector median) and Durables at 50 days (30% below). The cost backdrop also turned against shippers: WTI crude rose 8% to $94.5/barrel in first two weeks of September sustained Middle East risk premium, while spot trucking rates climbed 2% to $2.28/mile due to the inflationary pressure from the middle east conflict. On a positive note, Manufacturing PMI expanded in August. Consumer company margins face a converging with input and freight costs sticky on unresolved geopolitical risk, and a cautious consumer heading into a midterm cycle with unsettled trade policy.
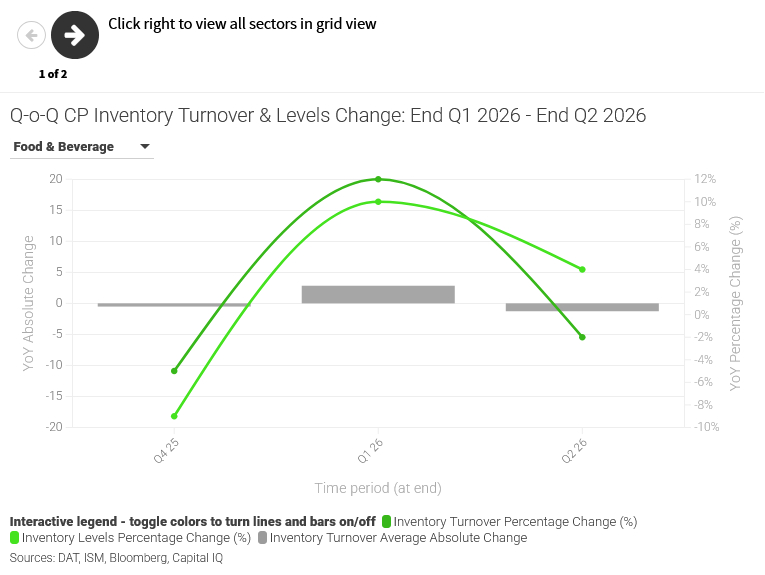
On a monthly basis, AlixPartners charts sales, sentiment and supply chains in consumer-facing businesses.
The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.
[View Source]